
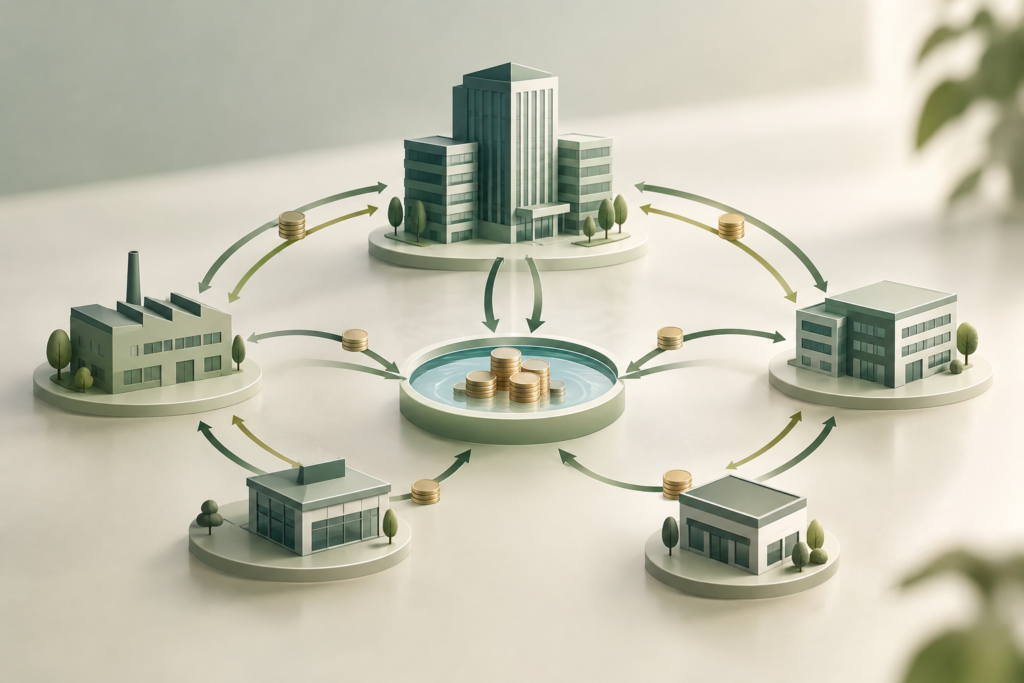
In many corporate groups, cash pooling systems run inconspicuously for years – until one company runs into difficulty. At that point at the latest, insolvency administrators, creditors and the public prosecutor’s office ask where the subsidiary’s liquidity went, whether it was remunerated and secured at arm’s length, and whether management should ever have permitted the outflows in the first place.
In short: every company participating in a cash pool remains a separate legal entity. A benefit to the group as a whole does not justify outflows of funds that harm the individual company, its creditors or its shareholders. This article shows when existing cash pooling structures can become legally problematic, which offences under the Austrian Criminal Code (StGB) may come into consideration, what liability managing directors and management board members may face, and how intra-group payment flows are forensically reconstructed.
Why do existing cash pooling structures become a legal risk?
With every transfer into the cash pool, the subsidiary exchanges a bank balance for an intra-group receivable. Whether this receivable is recoverable, enforceable and adequately remunerated determines its legal assessment. Particularly critical are pool receivables against debtors of weak creditworthiness, inadequate interest, excessive credit lines and repayment that is restricted in practice.
Even cash pooling that was initially justifiable can become critical if the creditworthiness of the cash pool leader deteriorates over time, or if balances grow persistently without limits and collateral being adjusted. It is precisely this gradual development that is often at the centre of subsequent civil and criminal disputes.
When is cash pooling not at arm’s length?
Cash pooling terms are not at arm’s length if independent companies would not have agreed to them under comparable circumstances. The decisive factor is not only the interest rate, but the overall package of function, risk, term, availability of funds, creditworthiness and remuneration.
Typical warning signs of a lack of arm’s length terms
- no interest, or clearly insufficient interest, on the subsidiary’s credit balances,
- no written cash pooling agreement, or a contract from which actual practice deviates,
- no credit limits, termination rights or rights of recall,
- short-term pool balances that in practice turn into long-term loans,
- no comprehensible interest methodology and no contemporaneous transfer pricing documentation.
What are the consequences of non-arm’s length terms?
From a tax perspective, the tax authorities may adjust the result, for example as a hidden profit distribution or a hidden capital contribution – with consequences for corporate income tax, withholding tax on capital gains and transfer pricing documentation. Incorrect tax returns may raise issues under fiscal criminal law, although not every transfer pricing discrepancy automatically constitutes a fiscal offence.
Under company law, an outflow of funds to the parent company or a benefiting group company without equivalent and commercially justified consideration may constitute a prohibited return of capital contributions under § 82 of the Austrian Limited Liability Companies Act (GmbHG). The Austrian Supreme Court (OGH) emphasises that the prohibition primarily concerns the company and its shareholders, but may be asserted against third parties if they acted collusively or if the violation must have been obvious to them. Moreover, the arm’s length test is not the sole decisive criterion under company law: what matters is whether a diligent managing director would have concluded and continued the agreement for this specific company on these specific terms.
Can cash pooling constitute breach of trust under § 153 StGB?
Yes. A person commits breach of trust if they knowingly abuse their authority to dispose of another’s assets or to bind another, thereby causing financial loss to that other person. Managing directors and management board members have authority over the company’s assets – passing on liquidity to affiliated companies is therefore a classic case for this examination.
When does an abuse of authority occur?
Since the Criminal Law Amendment Act 2015, a person abuses their authority if they violate, in an unjustifiable manner, rules that serve to protect the assets of the beneficial owner. “Unjustifiable” means conduct outside what can reasonably be argued. There is no abuse if the beneficial owner – in the case of corporations, the shareholders – consented to the act of representation in good time (i.e. before it was carried out).
Important for cash pooling: according to the legislative materials, a violation of rules that serve exclusively the interests of creditors does not constitute breach of trust; such cases are covered under criminal law by the insolvency offences and accounting offences. Shareholder consent therefore protects against an allegation of breach of trust, but not against insolvency offences or civil liability.
When does loss arise for breach of trust purposes?
Breach of trust requires an actual loss of assets; according to the legislative materials, a mere endangerment of assets is generally not sufficient. However, if liquidity is transferred to a group debtor that is already insolvent, there may, in economic terms, be a total loss at the moment of the outflow. According to case law, in the case of economically unjustifiable risk transactions, the loss occurs at the time the money is paid out. Outflows during a group crisis and in the absence of any assurance of repayment due to insufficient creditworthiness are therefore particularly critical.
The penalty increases with the amount of loss: for a loss exceeding EUR 5,000, the offender faces imprisonment of up to three years; for a loss exceeding EUR 300,000, imprisonment of one to ten years.
Does the business judgment rule offer protection?
§ 25(1a) GmbHG and § 84(1a) of the Austrian Stock Corporation Act (AktG) create a safe harbour: anyone who, in making a business decision, is not guided by extraneous interests and may reasonably assume, on the basis of adequate information, that they are acting in the best interests of the company is acting with due care. The prerequisite is a documented decision aligned with the interests of the director’s own company – not merely those of the group.
When do cash pooling outflows constitute insolvency offences?
The insolvency offences (Kridadelikte) under §§ 156 et seq. StGB protect the company’s creditors. Under § 161 StGB, executive employees of a legal entity – in particular managing directors and management board members – are punished in the same way as a debtor (i.e. here, the company).
Fraudulent insolvency (§ 156 StGB)
A person commits fraudulent insolvency (betrügerische Krida) if they conceal, remove, dispose of or otherwise actually or fictitiously reduce their assets, thereby frustrating or diminishing the satisfaction of their creditors. According to case law, it is also sufficient to reduce the assets without corresponding consideration. Neither insolvency proceedings nor illiquidity are a prerequisite. In cash pooling, this may concern, for example, the deliberate transfer of liquidity in exchange for a recognisably worthless intra-group receivable. The penalty ranges from six months to five years’ imprisonment, and from one to ten years for a loss exceeding EUR 300,000.
Preferential treatment of a creditor (§ 158 StGB)
A person is liable to punishment if, after becoming illiquid, they favour one creditor and thereby disadvantage the others (imprisonment of up to two years). This becomes relevant where a subsidiary that is already illiquid gives priority to settling liabilities towards the cash pool or the parent company while external creditors receive nothing.
Grossly negligent impairment of creditors’ interests (§ 159 StGB)
A person is liable to punishment if, through gross negligence, they bring about their own illiquidity by conduct typical of insolvency offences, or if, knowing or negligently unaware of their illiquidity, they frustrate or diminish the satisfaction of creditors. Such conduct includes, contrary to the principles of proper business management, squandering or giving away significant assets. This is the key risk for managing directors who permit liquidity outflows into the pool without examining creditworthiness and without limits. Where the creditors’ shortfall exceeds EUR 1,000,000, the maximum penalty increases from one year to two years’ imprisonment.
Note: Since 2024, final convictions for breach of trust or insolvency offences resulting in a prison sentence of more than six months also lead to disqualification from acting as managing director or management board member for three years (§ 15(1a) GmbHG, § 75(2a) AktG).
What liability do managing directors and management board members face?
Civil liability
- Internal liability towards the company under § 25 GmbHG or § 84 AktG – according to case law, an organisational responsibility rather than pure liability for outcomes.
- Claims for reimbursement due to prohibited return of capital contributions, which in the event of insolvency are regularly pursued by the insolvency administrator.
- External liability towards creditors under § 1311 of the Austrian Civil Code (ABGB): according to case law, § 159 StGB is a protective statute in favour of creditors.
Criminal liability
In addition to breach of trust and insolvency offences, accounting offences (§ 163a StGB) and possibly fiscal offences under the Fiscal Offences Act (FinStrG) may come into consideration, depending on the facts. Other participants – such as group executives who order outflows – may also be held liable as accessories. Instructions from the group do not exonerate the subsidiary’s corporate bodies: they must be able to identify which amounts flow to which debtor, how that debtor’s creditworthiness is assessed and what measures apply if it deteriorates.
What duties apply in a corporate crisis?
In a crisis, the requirements become stricter. Managing directors must continuously monitor pool balances, exercise rights of recall in good time, adjust limits and collateral, and critically examine payments to the pool where illiquidity is imminent. Each of these decisions should be documented in a comprehensible manner.
How are intra-group payment flows forensically investigated?
Forensic investigation means reconstructing all intra-group flows of funds without gaps, assigning the respective legal basis to each, and assessing the recoverability of the resulting receivables at the relevant point in time. The result must be comprehensible and robust for courts, public prosecutors and insolvency administrators.
Which methods are used?
- Data collection and preservation: bank statements, the bank’s cash pool reports, accounting data, clearing accounts, contracts, resolutions and email correspondence.
- Reconstruction of payment flows: reconciliation of bank data with clearing accounts at the level of each company; visualisation as a flow of funds analysis.
- Balance development and timeline: illustration of when balances grew and from what point the pool debtor’s creditworthiness deteriorated.
- Recoverability assessment: assessment of intra-group receivables at the critical reference dates, in particular before and after the onset of illiquidity.
- Contract vs. practice comparison: examination of whether interest was actually charged, limits were observed and recalls were possible.
- Loss determination and documentation: quantification of potential losses or creditor shortfalls and court-proof preparation in an expert report.
What should be considered when reviewing existing cash pooling agreements?
A contract alone is not sufficient if operational practice deviates from it. In our legal assessment, we examine in particular:
| Review point | Critical questions |
| Terms and termination | Does the subsidiary have termination rights? Are balances short-term or effectively tied up long-term? |
| Repayment | Can the subsidiary recall funds at any time for operational purposes? Has this been tested in practice? |
| Interest | Is the interest rate at arm’s length and commensurate with the risk? Is it actually booked? |
| Limits and monitoring | Are there credit limits, information rights and early warning mechanisms? |
| Documentation | Are there written contracts, resolutions, instructions and transfer pricing documentation? |
How does KINDL.trusted support you?
KINDL.trusted combines white-collar and fiscal criminal law, fraud investigation, forensic accounting and tax advisory services. In connection with cash pooling, we are particularly active in:
- legal advice and defence in cases of suspected breach of trust or insolvency offences – for managing directors, management board members and companies,
- forensic analysis and reconstruction of intra-group payment flows, including expert reports for criminal, civil and insolvency proceedings,
- legal review and assessment of existing cash pooling and group financing agreements,
- assessment of arm’s length terms and of tax and fiscal criminal law risks.
Conclusion: cash pooling needs control – before the crisis hits
Existing cash pooling structures do not run themselves. A lack of arm’s length terms, unsecured balances and outflows during a crisis can give rise to breach of trust, fraudulent insolvency, preferential treatment of creditors or grossly negligent impairment of creditors’ interests – and make managing directors personally liable. Early legal review and clean forensic documentation of payment flows are the most effective protection.
Do you have doubts about your cash pooling structure, or are you facing an allegation? Talk to KINDL.trusted – we review contracts and payment flows before liquidity management turns into a liability or criminal law risk.
Contact
Your contact from our KINDL.Legal Defense practice area:
Marc Julian MAYERHÖFER
Partner | Rechtsanwalt
